Brazilian banks' profits rose and reached the historic milestone of R$ 255 billion in 2025, a new record. The figures are from the Central Bank. The increase occurred in a year in which the economy's benchmark interest rate, set by the Central Bank to curb inflation, rose to 15% per year – the highest level in nearly 20 years, and one of the highest in the world in real terms.
Interest rates only began to recede in 2026. The Selic rate serves as the basis for banks in their loans, which, excluding lines with subsidized rates (directed credit), have much higher interest rates than the economy's benchmark rate. In some credit lines, such as revolving credit card debt, most used last year, and overdraft protection, interest rates exceed 400% and 100% per year, respectively.
Another characteristic of the Brazilian banking sector is that it is highly concentrated, with the four largest banks grabbing nearly 60% of the credit market in 2024. Contacted by g1, the Central Bank evaluated that, in 2025, the growth of net income for Brazilian banks was "more moderate," and "profitability remained relatively stable." "This behavior reflects, above all, the increase in provision expenses, which partially offset the interest result, whose growth slowed down due to lower credit expansion.
Thus, profit growth remained aligned with the pace of expansion of the national financial system's total assets," says the Central Bank. Customers can contest undue charges made by banks High profitability At the same time, the so-called return on equity (ROE), which measures how much profit a company makes relative to the value invested by shareholders, advanced to 16.76% in 2025. This is the highest level since 2021, when it totaled 17.55%, according to the BC. According to a survey by Canada's Office of the Superintendent of Financial Institutions (OSFI) – an independent federal agency responsible for bank supervision – the profitability of Brazilian banks is also well above their peers in developed countries. OSFI highlighted in its study that international comparisons of bank profitability should be interpreted with caution, as they are influenced by differences in leverage, business models, market structures, and regulatory rules in each country. The Director of Economy, Prudential Regulation, and Risks at the Brazilian Federation of Banks (Febraban), Rubens Sardenberg, said that the profitability level of the Brazilian banking sector is aligned with other emerging countries.
He considered data from the publication The Banker (Top 1000 world banks, from the Financial Times). "The average ROE of Brazilian banks in the sample is 16.5%, for a 5-year period average between 2020-24, below countries like Mexico, Peru, and South Africa (in addition to Argentina and Turkey, which have higher inflation levels and can distort the comparison)," says Rubens Sardenberg, from Febraban. Diversification and digitalization According to Einar Rivero, financial data specialist and CEO of consulting firm Elos Ayta, the banking system closed 2025 at a new level of profitability, reflecting the ability of financial institutions to generate revenues in an increasingly diversified manner, combining credit operations, financial services, asset management, insurance, and capital markets. "Although the Selic rate was an important component of this trajectory, attributing performance exclusively to high interest rates would be an oversimplification," Einar Rivero said. "The results for 2025 were driven by the combination of still high spreads [the amount banks charge above what they pay to raise funds], a gradual reduction in default rates compared to previous years, greater discipline in credit granting, and significant advances in operational efficiency," the specialist added. According to him, the financial sector also reaped the rewards of investments made in recent years in digitalization, process automation, and the improvement of risk management models — factors that contributed to increasing productivity and reducing structural costs. "Another relevant aspect is that the record profit was achieved in a more diversified financial system than in the past.
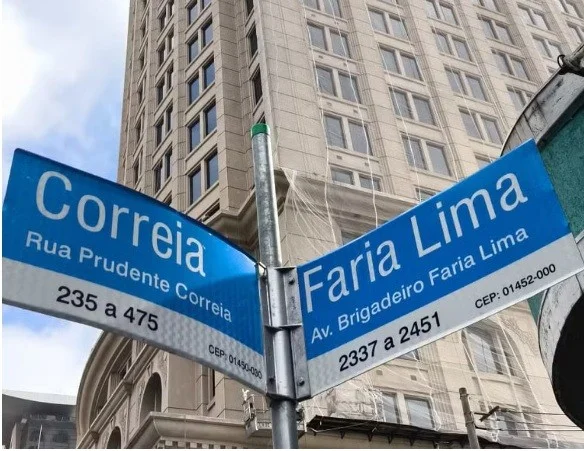
The growth in the share of business models focused on wealth management, capital markets, and high-income clients made the results less dependent on the traditional credit cycle," the analyst concluded. The Union of Bank Workers of São Paulo, Osasco, and Region noted that: Since 2020, with the intensification of the digitalization of financial services, the banking sector has cut 31,300 jobs through April 2026, of which approximately 25,000 were held by women; The number of bank branches has dropped 37% in ten years in Brazil, falling to just over 14,000, amid the advance of technology to carry out transactions and banks' decisions to cut costs; Since 2015, 638 municipalities have been left without a bank branch, leaving 6.9 million people underserved, according to calculations by Dieese. High interest rates do not help banks, says Febraban Sign of Avenida Brigadeiro Faria Lima, in the South Zone of São Paulo, the country's main financial center David Irikura/TV Globo For Rubens Sardenberg, director at Febraban, it is a "misconception" to state that banks benefit from the high Selic rate. According to him, a high benchmark interest rate increases the institutions' cost of funding. "This environment tends to put pressure on default rates, meaning it increases losses from credit operations, causing financial institutions to be more conservative in the credit-granting process," Sardenberg said. "This limits the growth of the credit portfolio and limits the country's economic growth, which curbs not only the advance of revenues originating from credit, but also revenues from services, such as in capital market operations," the Febraban director added. He also cites BC data showing that 80% of the so-called "bank spread" (the amount charged in addition to the Selic rate on credit lines) is composed of costs such as default expenses (35.4%), administrative expenses (23.3%), and taxes (21%).
And he evaluated that the "financial margin" (20.3%) is the smallest fraction of credit operation spreads. Regarding the controversy over PIX with the United States, the director noted that, on one hand, the tool generates an increase in bank adoption, which contributes to the growth and strengthening of the financial market and business. On the other hand, it promotes cost reductions for bank customers (with a potential drop in revenues from this service). "It is difficult to estimate the net impact [of PIX on the financial system], which requires more in-depth studies.
But our initial impression is that the outcome of PIX implementation is positive for banks," Rubens Sardenberg concluded.
Sign in to comment on this article.
No approved comments yet.